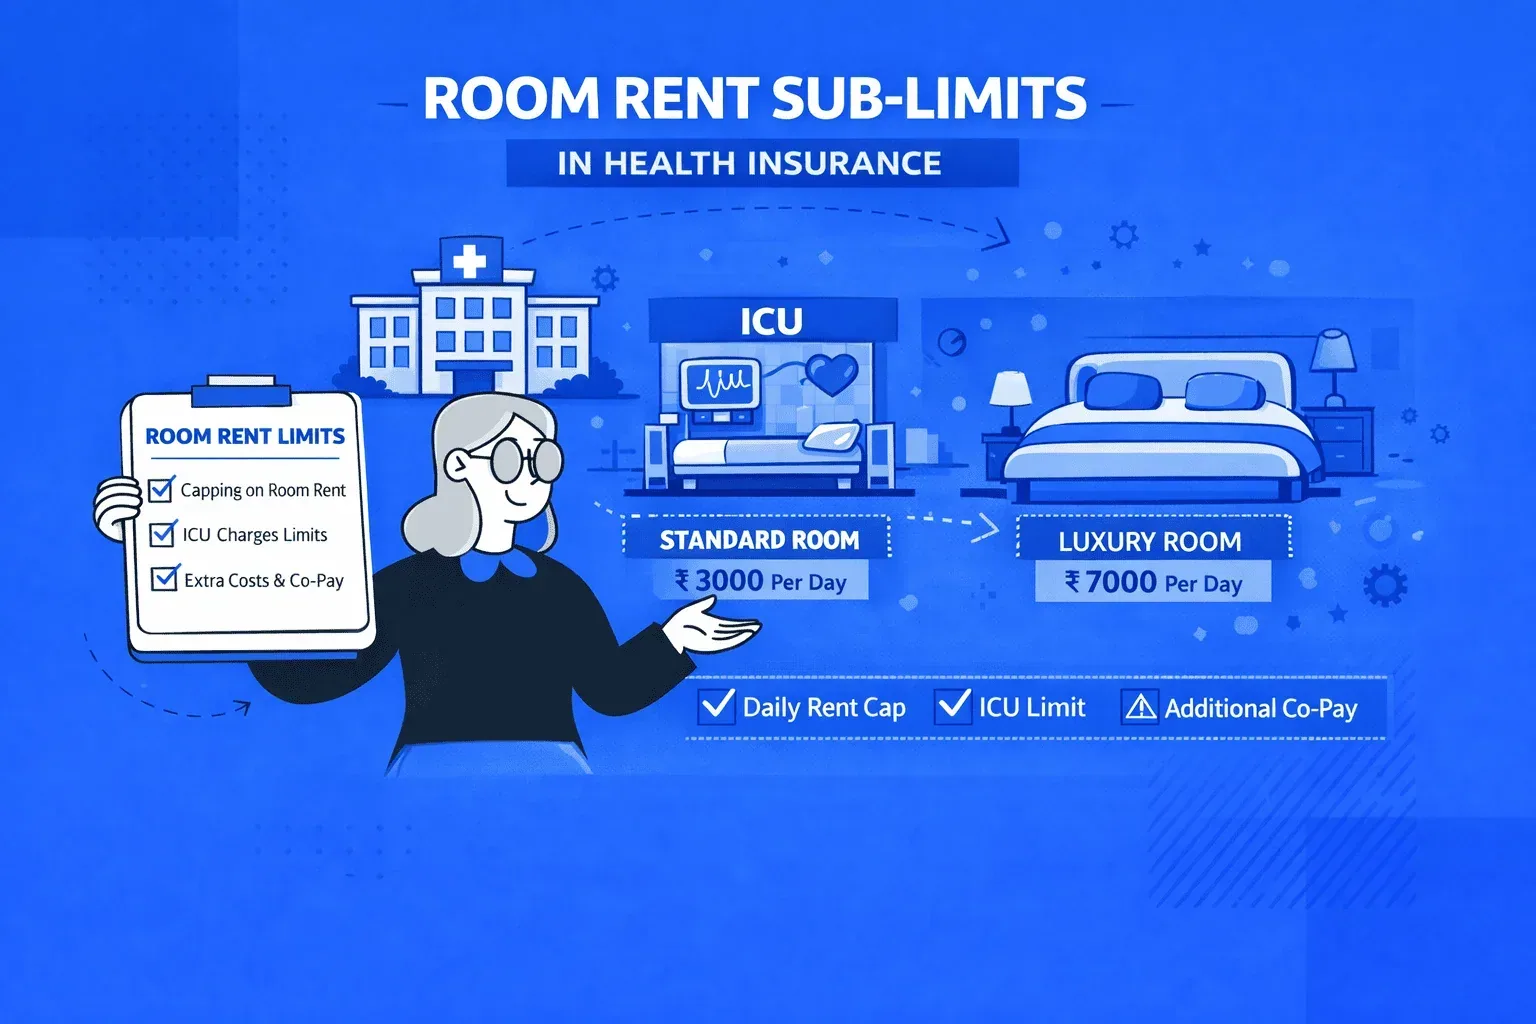
Health insurance plans can look similar at first glance, yet the finer policy terms often decide how useful the cover feels during an actual hospital stay. Room rent limits, treatment-related sub-limits and restoration benefits can all affect how a claim works and how much you may need to pay yourself.
Looking at these features together gives you a more practical basis for comparison, especially when you want a policy that fits both your everyday healthcare needs and larger hospitalisation expenses.
Room Rent Limits
Room rent is the amount or category of hospital room that a policy allows during hospitalisation. Some plans may provide a defined limit, while others may offer broader room eligibility depending on the policy terms.
This feature deserves attention because room choice can influence how certain associated charges are handled during a claim. It is useful to read this clause before focusing only on the mediclaim premium shown for the plan.
What to Compare
Check how the policy describes room eligibility and whether the limit applies as a fixed amount, a percentage-linked condition or a room-category condition. Also review intensive care accommodation, since its terms may differ from regular room eligibility.
- Check the permitted room category.
- Review whether intensive care has separate terms.
- See whether the plan places conditions on room upgrades.
- Read the policy wording for linked hospital charges.
Why It Matters
A room rent clause can affect more than the room bill alone. Depending on the policy structure, choosing a room outside the permitted category may influence how associated hospital expenses are assessed. A plan with broader room eligibility may offer more flexibility during hospitalisation, although the exact treatment of claims depends on the policy wording.
- It can affect your choice of hospital room.
- It may influence the amount payable from your pocket.
- It helps you understand claim conditions before admission.
- It makes comparison more meaningful than looking at premium alone.
Disease and Treatment Sub-Limits
Sub-limits place a defined ceiling on specific expenses, treatments or medical procedures within the overall sum insured. They may limit how much can be claimed for a particular item. Since different plans may apply them differently, this is an important area to review when comparing overall coverage quality.
What to Compare
Look at whether the plan specifies limits for particular treatments, procedures, room-related expenses or other healthcare categories. The exact list can vary between policies, so the schedule of benefits and policy wording should be checked together.
- Identify treatments that carry separate limits.
- Check whether limits apply per claim or policy period.
- Review whether specific medical expenses have separate caps.
- See how sub-limits interact with the overall sum insured.
Why It Matters
Two policies with the same sum insured may work differently when a specific treatment is required. A sub-limit can determine how much of that expense is considered under the policy, which may affect your personal contribution to the hospital bill.
- It helps set realistic expectations before treatment.
- It shows how much usable cover applies to specific needs.
- It can be relevant for planned procedures.
- It adds an important layer to policy comparison.
Restoration Benefit
The restoration benefit is designed to replenish the sum insured after it has been partly or fully used, subject to policy conditions. This feature can be helpful when more than one hospitalisation occurs during the same policy period. However, restoration rules vary by plan, so it is important to understand when the benefit is available and how it can be used.
What to Compare
Read the restoration clause carefully instead of relying only on the presence of the feature. Check the trigger for restoration, whether it applies after partial or complete utilisation and whether there are conditions on using the restored amount.
- Check when restoration becomes active.
- Review whether it applies after partial or full utilisation.
- See whether restored cover can be used for the same illness.
- Check whether the benefit can be used more than once.
- Read all conditions linked to the restored sum insured.
Why It Matters
A restoration benefit can add flexibility when the original sum insured is used during the policy period. It may be useful for family policies, where more than one insured member could need hospitalisation at different times. The real value, however, depends on the conditions attached to restoration.
- It can provide an additional layer of available cover.
- It may support multiple hospitalisation needs in one policy period.
- It helps you look beyond the feature name.
- It shows how each plan behaves after a major claim.
Conclusion
A useful health insurance comparison goes beyond premium and total sum insured. Room rent limits show how much flexibility you may have during hospitalisation, sub-limits explain how specific expenses are treated, and restoration benefits show what happens after the original cover is used.
Reading these clauses together can help you understand the practical value of a plan before buying it. Always review the latest policy wording, schedule and applicable conditions carefully, as benefits and claim treatment remain subject to policy terms.